Vyrao Sold to Tresalis: What a Undisclosed Acquisition Reveals About the $5.6B Niche Fragrance Market's Next Power Shift
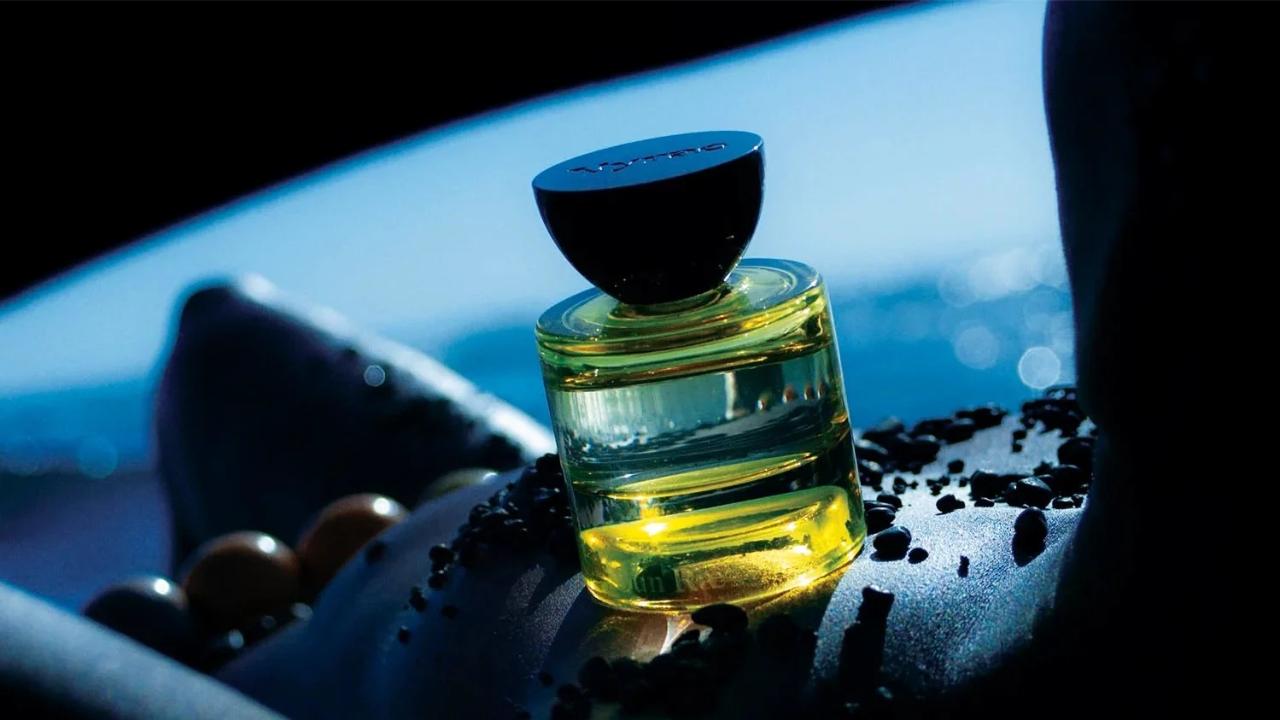
The global niche fragrance market is tracking toward $5.6 billion by 2027, compounding at roughly 9.2% CAGR, and the strategic transactions clustering around it are growing correspondingly more complex. Tresalis, a newly constituted beauty vehicle backed by German investment firm Athos, has acquired British fragrance brand Vyrao in a deal with undisclosed financials, closing a five-year capital journey that ran through Estée Lauder Companies' New Incubation Ventures, Manzanita Capital, and L Catterton's Elevate Beauty growth fund. The acquisition raises a question that matters more than any headline valuation: what does Tresalis actually intend to build, and does Vyrao's distribution architecture support a trajectory beyond its current prestige positioning?
The Capital Stack Behind Vyrao Was Always Pointing Toward an Exit
Vyrao was not built to stay independent indefinitely. Founder Yasmin Sewell, a former fashion buying executive, launched the brand in 2021 after a development period beginning in 2019, and the cap table assembled around it reads like a deliberate exit pathway. New Incubation Ventures entered at the 2022 seed round, returned in 2023 with a minority stake announcement, and participated again in the 2024 round led by Elevate Beauty, L Catterton's dedicated growth instrument for prestige consumer brands. L Catterton's involvement alone typically signals a three-to-five-year value creation thesis with a strategic buyer or IPO at the terminus. The Tresalis acquisition, arriving in late 2026, falls squarely within that window.
One path is consolidation upward, deepening distribution in GCC luxury retail corridors and pursuing placement with major APAC specialty retailers where niche fragrance is absorbing outsized wallet share from local prestige consumers.
The layered investor profile also tells a distribution story. New Incubation Ventures exists specifically to accelerate brands into the Estée Lauder Companies' retail and wholesale infrastructure or to prove out concepts that ELC's core portfolio cannot absorb organically. That Vyrao did not ultimately land inside ELC's own house suggests the brand's emotional wellness positioning, rooted in scent-mood architecture and genderless eau de parfums, sat outside ELC's current premiumization priorities rather than inside them.
Distribution Architecture Is the Real Acquisition Variable
Vyrao's retail footprint at acquisition reflects the strengths and constraints of a prestige indie fragrance label scaling cautiously through selective global doors. The brand carries placement in high-credibility specialty retail environments across the UK and selectively across APAC and MENA, but its wholesale reach has not achieved the density required to justify a masstige pivot. That matters because Tresalis, with no disclosed portfolio history and limited public positioning, faces a fundamental strategic fork.
One path is consolidation upward, deepening distribution in GCC luxury retail corridors and pursuing placement with major APAC specialty retailers where niche fragrance is absorbing outsized wallet share from local prestige consumers. The second is a portfolio reset that repositions Vyrao within a multi-brand structure Tresalis may be assembling, using the brand as an anchor for a broader wellness-adjacent fragrance play. Neither path is confirmed, but the Athos backing and the platform's deliberate construction suggest the second scenario carries more structural logic.
The brand carries placement in high-credibility specialty retail environments across the UK and selectively across APAC and MENA, but its wholesale reach has not achieved the density required to justify a masstige pivot.
Emotional Wellness as a Category Thesis, Not Just a Brand Story
Sewell built Vyrao around a conviction that scent and mood are commercially inseparable, a thesis that has since been validated by the broader market. The global emotional wellness segment, including functional fragrance, adaptogenic beauty, and mood-support personal care, is attracting institutional capital at a pace that mirrors the early trajectory of clean beauty investment between 2014 and 2019. Vyrao's ingredient selection framework, which weights both olfactory profile and purported wellbeing associations, positions the brand inside that thesis at a fine fragrance price tier.
The brand's expansion into incense and scented candles extends that thesis into home fragrance, a category growing at roughly 7.8% CAGR globally and increasingly treated as an adjacent SKU opportunity for prestige fragrance houses rather than a separate retail vertical. Tresalis inherits a multi-category footprint that, if activated through the right distribution architecture, could accelerate revenue without requiring a full product development cycle.
What Tresalis Does Next Will Define Whether This is Strategic Consolidation or a Portfolio Placeholder
The acquisition of Vyrao is not, by itself, a market-moving event. Undisclosed terms and an absent post-acquisition strategy statement from Tresalis limit any confident read on valuation or intent. What the deal does confirm is that premium wellness fragrance continues to attract institutional capital at a point in the M&A cycle when many category-adjacent assets are trading at compressed multiples. Athos-backed Tresalis entering the space now suggests either a contrarian conviction that niche fragrance premiumization has further structural runway, or a platform-building thesis that requires patient accumulation before any strategic consolidation becomes legible. The next 18 months, and whatever distribution decisions Tresalis makes in UK, GCC, and APAC channels, will answer that question directly.
This article references and builds on original reporting by Sophie Smith for The Industry Beauty. Read the original piece here: https://theindustry.beauty/vyrao-acquired-by-tresalis-in-new-chapter-for-british-fragrance-brand/. BeautyScale is a commercial agency; our editorial notes are commentary on industry reporting.
Josette Assaf
Beauty market analyst covering trends, brands, and distribution shifts.