K-Beauty and At-Home Devices Rewrite Retail Velocity: What Lookfantastic's 2026 Data Means for $650B Global Skincare Distribution
K-beauty SKU sales across THG Beauty's Lookfantastic platform surged 158% year-on-year in the first half of 2026, generating a customer cohort of 64,000 net-new buyers who returned at above-average repurchase rates, a signal that carries implications far beyond one retailer's sales dashboard. Against a backdrop of £500.2 million in THG Beauty revenue for H1 2026, up 5.9% on a constant-currency basis, the top-10 SKU ranking Lookfantastic released this month functions less as a bestseller list and more as a forward indicator for distribution architecture decisions across prestige and masstige tiers globally.
The pattern embedded in this data is structural. Three distinct product categories, barrier repair, at-home LED devices, and SPF-anchored daily protection, are consolidating into a core routine framework that is reorienting how high-traffic etailers curate assortment and how brand managers should think about SKU prioritization heading into 2027 planning cycles.
The K-Beauty Velocity Signal Is a Retail Strategy Problem, Not a Trend Story
Medicube's Zero Pore Pad 2.0 posted 919.9% sales growth at Lookfantastic, and Biodance's Bio Collagen Real Deep Mask grew 331.5%, figures that reflect accelerating consumer discovery velocity rather than steady-state category maturation. Beauty of Joseon, already the top performer in Lookfantastic's July 2026 summer travel ranking with its Relief Sun Rice + Probiotics SPF50+, recorded 77.3% growth in the broader period, reinforcing that K-beauty's penetration in Western etail is compounding, not plateauing.
For brand managers and category directors, the implication is immediate. Distribution architecture built around established prestige anchors, La Roche-Posay at number one with 81.9% growth and Elemis holding second at 2.6%, must now accommodate K-beauty challengers that are capturing disproportionate share of new customer acquisition. La Roche-Posay's ascent to third most-shopped brand on the platform, with overall brand sales up 64%, demonstrates that clinically-positioned, dermatologist-credentialed positioning commands durability. The K-beauty brands sitting beneath it are building toward the same credentialing trajectory at a faster pace.
LED Device Premiumization Is Entering the Replenishment Economy
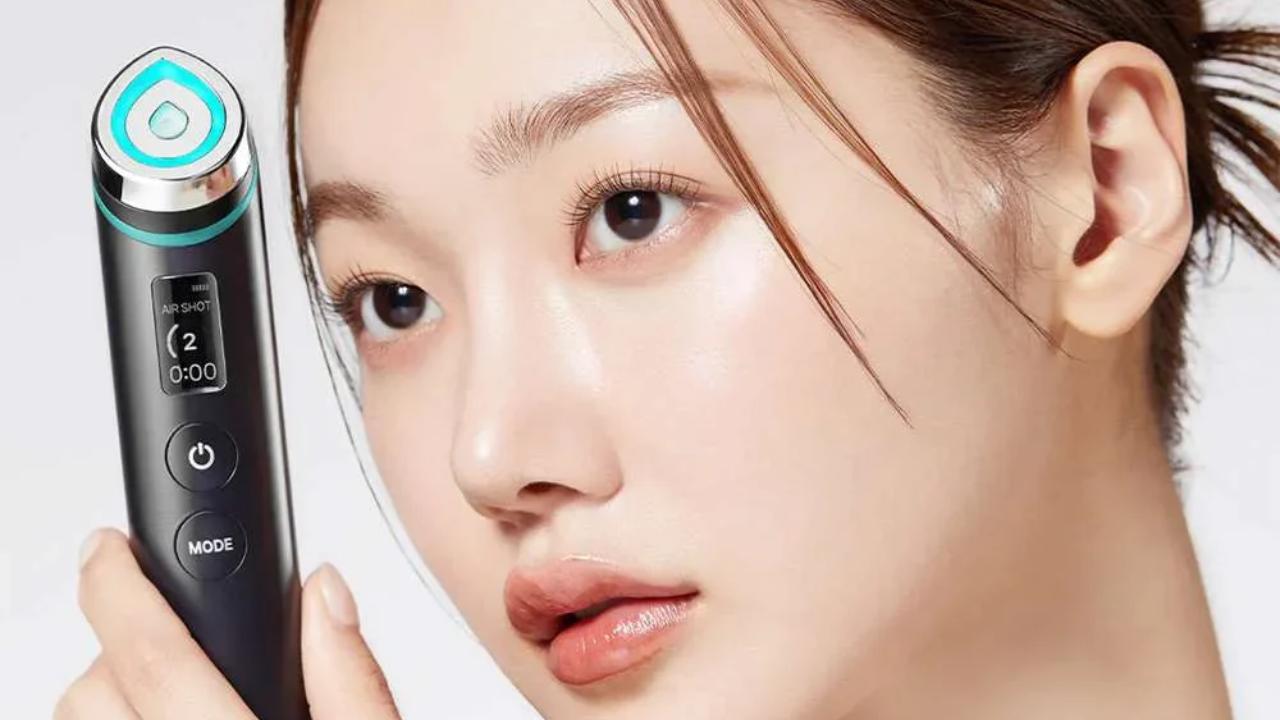
The Silk'n Facial LED Mask 100 LEDs ranked fourth with 158.9% growth, a data point that aligns with Lookfantastic's own AW26 trend report registering 101.3% sales growth for electrical skin devices. This is not incidental hardware enthusiasm. At-home LED adoption represents a structural shift in how consumers allocate skincare spend, moving capital from high-frequency consumable products toward durable device platforms with companion product ecosystems.
For portfolio strategists and M&A analysts, the device category's trajectory raises a direct question about vertical integration opportunity. Beauty conglomerates that have historically operated as pure formulation businesses now face a portfolio reset decision: build, license, or acquire device capabilities to defend basket size and repurchase frequency as device ownership grows. The brands best positioned for the next cycle are those that can engineer a device-plus-consumable architecture into their retail presence before platform gatekeepers do it for them.
SPF's Reclassification Changes Category Investment Logic
Three SPF products appearing in Lookfantastic's top 10, including La Roche-Posay's Anthelios UVMune 400 Invisible Fluid SPF50+ at 27.2% growth and Elemis Pro-Collagen Marine Cream SPF 30 at 12.6%, confirms a category reclassification that brands and retailers have been anticipating for several years. SPF has completed its migration from seasonal, occasion-driven SKU to anchor product in daily morning routines, competing directly for the slot historically owned by moisturizer.
This reclassification compresses margin opportunity in one sense (SPF as commodity protection) while opening premiumization positioning in another (SPF as prestige skincare with bioactive delivery). Brands that move early to reposition their SPF architecture within prestige skincare pricing corridors, above the pharmacy channel, below the luxury skincare ceiling, will capture the most defensible shelf position as the category attracts new entrants.
THG's Distribution Footprint Becomes the Strategic Variable
THG Beauty's Lookfantastic platform is functioning as a launch amplifier for challenger K-beauty brands at a scale that regional distributors and specialty retailers cannot easily replicate. As THG continues to identify Lookfantastic as its primary revenue driver, the platform's curation decisions will increasingly shape which emerging brands achieve Western distribution critical mass, and which remain confined to domestic APAC performance.
For investors and acquirers evaluating K-beauty assets, the Lookfantastic velocity data provides a rare public benchmark for assessing brand scalability in Western etail before a brand reaches traditional M&A visibility thresholds. The next significant K-beauty acquisition target is likely already in this top-10 list's shadow, compounding at triple-digit growth rates and building the new-customer cohort depth that makes a strategic multiple defensible.
Rayane Mahmoud
Beauty market analyst covering trends, brands, and distribution shifts.