The Niche Fragrance Paradox: $4.5B in Prestige Ambition, Fractured by Its Own Distribution Architecture
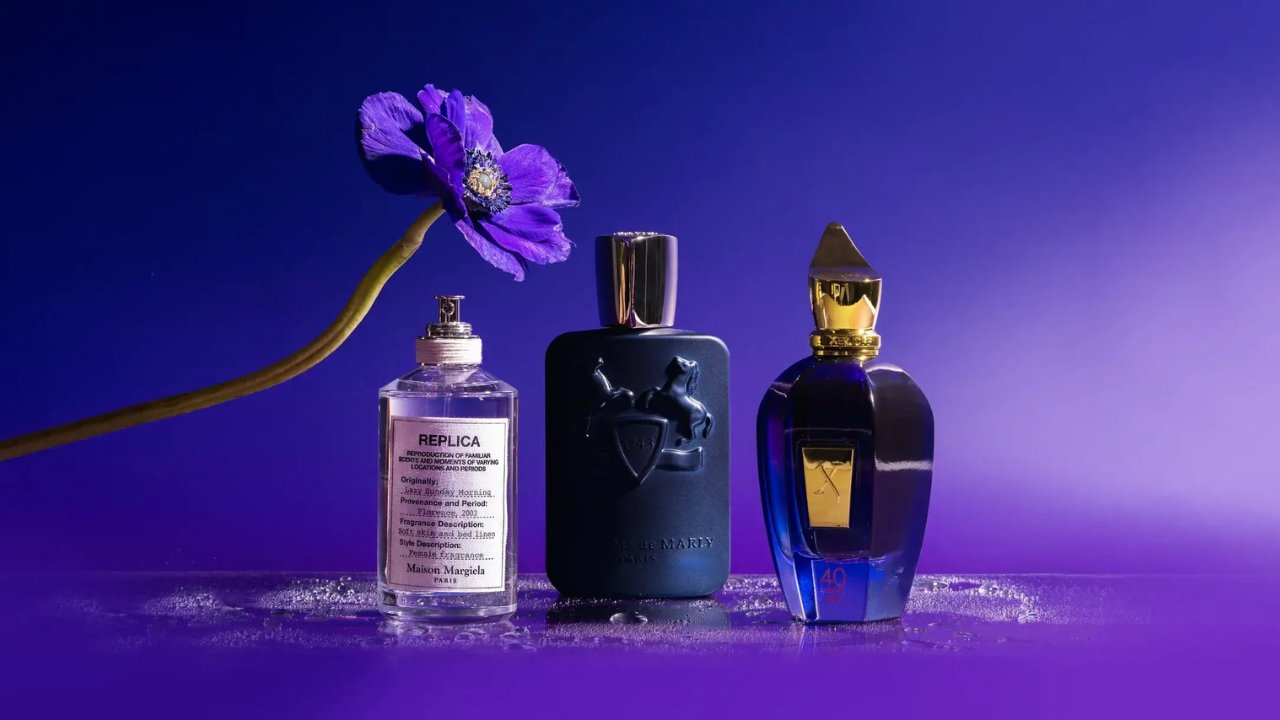
The global niche fragrance market reached an estimated $4.5 billion in 2023, posting a compound annual growth rate of 11.2 percent since 2018, yet the segment's most celebrated brands are arriving at a structural inflection point that no volume target can resolve. Exclusivity, the core value proposition that justified $300-plus price points and cultivated devoted collector communities, is increasingly in tension with the revenue thresholds required to attract serious M&A attention, sustain omnichannel infrastructure, and compete for shelf presence in an increasingly consolidated retail environment. The paradox is not merely philosophical. It has direct consequences for brand valuation, exit strategy, and the long-term viability of founder-led fragrance houses operating without the capital architecture of a Puig, Estée Lauder Companies, or L'Oréal Groupe behind them.
Prestige Positioning Erodes the Moment Distribution Scales
The founding logic of niche fragrance is deliberately anti-mass. Brands such as Creed, Byredo, and Le Labo built equity through scarcity, selective retail, and a narrative of artisanal inaccessibility. That logic performs exceptionally well at launch and through the early growth phase, generating strong gross margins and outsized brand heat relative to media spend. The problem surfaces at scale. When Byredo entered Sephora's North American distribution network, the brand's prestige positioning faced immediate consumer reappraisal. The distribution architecture that drives revenue competes directly with the exclusivity architecture that drives pricing power.
Le Labo's acquisition by Estée Lauder Companies in 2014 for an undisclosed but widely estimated mid-nine-figure sum demonstrated one viable path. ELC preserved the brand's distribution discipline with remarkable precision, maintaining the made-to-order ritual and limited door count as non-negotiables. That model has not been widely replicated. Most niche founders lack the negotiating leverage to impose post-acquisition brand governance terms, and most acquirers lack the patience to manage a brand that deliberately resists scale.
The M&A Calculus Has Shifted Against Founder-Led Houses
Strategic consolidation in fragrance accelerated meaningfully between 2020 and 2024, with Puig's acquisition of Dries Van Noten's fragrance license, Kering's deepened commitment to Creed following its 2023 acquisition, and LVMH's continued portfolio optimization across Parfums Christian Dior and Maison Francis Kurkdjian. These transactions collectively signal that the acquirer community is prioritizing fragrance assets with proven prestige positioning, existing APAC and GCC penetration, and clean distribution histories. Brands that compromised their retail selectivity in pursuit of near-term revenue have complicated their own exit narratives.
A brand generating $40 million in annual net sales through 200-plus wholesale doors trades at a meaningfully lower multiple than a comparable revenue brand distributed through 60 curated doors with direct-to-consumer accounting for 35 percent of the mix. The distribution architecture is not incidental to valuation. It is a primary variable. Investors from Advent International to L Catterton are applying this lens with increasing precision as the niche fragrance acquisition pipeline grows more competitive and due diligence timelines compress.
Masstige Pressure Is Redefining the Competitive Floor
The premiumization trend reshaping mass retail has introduced a new competitive dynamic that niche houses cannot afford to ignore. Retailers including Ulta Beauty and Douglas in the EMEA corridor have built dedicated prestige fragrance environments that blur the boundary between accessible luxury and genuine niche. Brands positioned in the $80-to-$150 price corridor, including Kayali and Maison Margiela's Replica line, are capturing consumers who previously represented the recruitment pipeline for true niche fragrance. The masstige segment is not simply growing. It is absorbing the aspirational consumer that niche fragrance historically converted to a loyalist over a 24-to-36 month discovery journey.
Niche houses that respond by lowering entry price points risk structural margin compression. Those that hold price while losing recruitment volume face a long-term customer aging problem that no marketing investment fully corrects.
The Brands That Navigate This Will Treat Distribution as Brand Strategy
The niche fragrance segment will bifurcate over the next five years into two distinct cohorts. The first will pursue institutional capital, accept controlled distribution expansion, and build the operational infrastructure required for an acquirer to pay a premium multiple without inheriting complexity. The second will remain deliberately micro, servicing a collector community, maintaining sub-$10 million revenue, and functioning as cultural assets rather than financial ones.
The brands that fail are those attempting to operate in the space between these positions, scaling distribution opportunistically without a coherent architecture and eroding the exclusivity premium that justified their valuation thesis from the outset. As GCC markets mature into the world's most competitive niche fragrance arena and APAC consumer sophistication accelerates, the window to establish clean distribution discipline is narrowing. Founders and brand managers who treat channel strategy as a tactical afterthought rather than a core brand governance decision will find that the market has made the choice for them.
Martin Jacob
Beauty market analyst covering trends, brands, and distribution shifts.